

Blogs
Market Overview
The global Blood and Organ Bank Market was valued at USD 18.51 billion in 2025 and is projected to reach nearly USD 29.72 billion by 2034, growing at a compound annual growth rate (CAGR) of 5.4% during the forecast period from 2026 to 2034. Market growth is supported by the increasing demand for blood transfusions, organ transplantation, tissue preservation, and advanced healthcare services. Technological improvements in blood collection, storage, compatibility testing, and organ preservation are also contributing to the expansion of the industry.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/230114/
Blood and organ banks are essential components of modern healthcare infrastructure. Blood banks collect, test, process, store, and distribute blood and its components for use in surgical procedures, trauma care, cancer treatment, and the management of chronic diseases. Organ banks and associated transplant organizations coordinate organ procurement, preservation, compatibility assessment, and allocation for transplantation. Tissue banks, umbilical cord blood banks, and bone marrow banking facilities further support medical treatments by providing biological materials for specialized clinical applications.
The growing prevalence of chronic diseases, including kidney failure, liver disorders, cardiovascular diseases, and certain cancers, is increasing the need for transfusions and transplantation procedures. An aging population and improvements in diagnostic capabilities are further expanding the potential patient population. At the same time, healthcare providers are emphasizing patient blood management, donor safety, traceability, and efficient utilization of collected biological materials.
Digital technologies are becoming increasingly important in blood and organ banking operations. Automated inventory management, temperature monitoring, electronic donor registries, and advanced compatibility testing can help improve operational efficiency and reduce avoidable losses. These technologies also support better coordination among hospitals, laboratories, collection centers, and transplantation networks.
Despite these positive developments, the market continues to face challenges associated with donor shortages, uneven access to healthcare infrastructure, regulatory compliance, storage requirements, and the time-sensitive nature of biological materials. Addressing these challenges will be important for ensuring a safe and reliable supply of blood, organs, and tissues throughout the forecast period.
Market Drivers and Trends
Rising Demand for Blood Transfusions and Organ Transplantation
The increasing incidence of chronic diseases and complex medical conditions is a major factor supporting the growth of the Blood and Organ Bank Market. Patients undergoing major surgery, cancer treatment, emergency trauma care, and treatment for blood-related disorders frequently require transfusions or specialized biological products. Similarly, individuals with end-stage organ failure may require kidney, liver, heart, lung, or other organ transplants.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/230114/
The expansion of transplant services has increased the importance of coordinated blood and organ banking systems. Transplant procedures require reliable access to compatible blood products, timely donor-recipient matching, and appropriate preservation technologies. As healthcare systems improve their capacity to perform complex procedures, demand for specialized banking and distribution services is expected to increase.
Government Initiatives and Public Awareness Campaigns
Government policies, public awareness programs, and nonprofit initiatives play an important role in encouraging voluntary blood donation and organ donor registration. Educational campaigns help address misconceptions surrounding donation and communicate its importance in saving lives. Governments and healthcare organizations also support donor registration systems, collection infrastructure, screening facilities, and coordinated transplant networks.
Improved public participation can help healthcare providers maintain more dependable supplies of blood and blood components. In organ transplantation, stronger donor registration systems and effective coordination between procurement organizations and hospitals can improve the identification and allocation of available organs. Continued investment in these programs is expected to support market development, particularly in regions where donation rates and banking infrastructure remain limited.
Technological Advancements in Banking and Preservation
Technological innovation is transforming the collection, testing, storage, and distribution of blood and organs. Modern blood bank refrigeration systems can incorporate digital temperature sensors, automated alarms, access controls, and connected monitoring platforms. Radio-frequency identification (RFID), barcode systems, and inventory management software can improve the traceability of blood units and help staff monitor expiration dates and storage conditions.
Advanced laboratory testing also supports safer transfusion practices. Molecular blood group typing and improved compatibility testing can help identify clinically relevant blood group characteristics and reduce certain transfusion-related risks. In organ transplantation, advanced histocompatibility testing and donor-recipient matching technologies support clinical decision-making.
Organ preservation technologies, including machine perfusion, are also attracting attention because they can help maintain organ function and allow clinical teams to assess organ suitability before transplantation. Their adoption depends on clinical requirements, cost, regulatory approval, and the availability of trained personnel. Nevertheless, continued innovation in preservation and monitoring is creating opportunities for specialized equipment manufacturers, diagnostic companies, and banking service providers.
Increasing Adoption of Digital Inventory Management
The management of biological materials requires accurate records, controlled storage conditions, and timely distribution. Digital inventory systems enable blood banks and healthcare facilities to monitor stock levels, identify shortages, track product movement, and improve coordination between collection centers and hospitals.
Smart refrigeration units and connected monitoring systems can provide alerts when temperatures move outside permitted ranges. These capabilities help staff respond quickly to equipment failures and reduce the risk of product wastage. Electronic donor registries and integrated laboratory information systems can also streamline workflows and improve record accessibility.
As healthcare providers focus on operational efficiency and quality assurance, investment in digital banking infrastructure is expected to create additional opportunities for technology suppliers and service providers.
Growth of Cord Blood, Tissue, and Bone Marrow Banking
Beyond conventional blood banking and organ transplantation, cord blood, tissue, and bone marrow banking are expanding the scope of the market. Cord blood contains hematopoietic stem cells that may be used in selected treatments for blood disorders and other conditions. Bone marrow banking and related donor registries support stem cell transplantation, while tissue banks provide materials used in reconstructive surgery, orthopedic procedures, and other medical applications.
Growing awareness of regenerative medicine and cellular therapies is encouraging interest in specialized storage and processing services. However, demand varies according to clinical indications, collection practices, regulatory frameworks, and the availability of compatible donors. Providers that maintain strong quality systems and reliable preservation infrastructure may be better positioned to serve these specialized healthcare needs.
Primary Market Constraints
Shortage of Blood and Organ Donors
The persistent gap between the availability of donated biological materials and clinical demand remains a significant challenge for the market. Blood collection can be affected by seasonal changes, public emergencies, donor eligibility restrictions, and insufficient participation in voluntary donation programs. Maintaining an adequate supply of different blood groups and components requires continuous recruitment and retention of eligible donors.
Organ donation faces additional challenges because organ availability depends on medical suitability, donor consent, legal requirements, and timely procurement. Many patients continue to face extended waiting periods for transplantation. Although awareness campaigns and improved donor registration systems can help, the supply of transplantable organs remains difficult to expand rapidly.
High Infrastructure and Operational Costs
Blood and organ banking require specialized facilities, refrigeration equipment, laboratory testing systems, trained professionals, transportation arrangements, and quality management procedures. Organ preservation can involve additional expenses associated with procurement coordination, specialized perfusion equipment, and rapid transportation.
Smaller healthcare facilities and organizations operating in resource-constrained regions may struggle to fund these requirements. The cost of installing and maintaining modern equipment can limit technology adoption, while ongoing expenditure on staffing, validation, maintenance, and regulatory compliance adds to operational pressure.
Regulatory and Quality Compliance Requirements
Blood, organs, tissues, and related biological products are subject to stringent safety and quality requirements. Facilities must follow applicable rules for donor eligibility, infectious disease screening, collection, processing, labeling, storage, transportation, and traceability. Organ transplantation also involves consent, allocation, compatibility assessment, and ethical considerations.
Compliance requires regular monitoring, documentation, staff training, equipment validation, and quality audits. Differences in regulatory frameworks across countries can complicate international collaboration and the development of standardized operating procedures. Failure to maintain appropriate controls can compromise patient safety and damage public confidence in donation programs.
Logistical and Preservation Challenges
Blood products and transplantable organs have specific storage and handling requirements. Temperature deviations, transportation delays, equipment failures, and inadequate coordination can reduce the usability of biological materials. Organs intended for transplantation are particularly time-sensitive, making rapid communication and effective logistics essential.
Healthcare networks must coordinate donors, laboratories, transport providers, surgical teams, and receiving hospitals. Limited transportation infrastructure and shortages of specialized personnel can create additional difficulties, particularly in rural and remote areas. Investment in resilient cold-chain systems, digital tracking, and emergency distribution planning will remain important for reducing these constraints.
Ethical, Cultural, and Public Confidence Issues
Public perceptions, religious and cultural beliefs, concerns about medical procedures, and uncertainty regarding consent can influence donation decisions. Inadequate communication or a lack of transparency may discourage participation in donation programs.
Healthcare organizations and governments must therefore emphasize informed consent, ethical allocation, privacy protection, and clear communication with donors and their families. Building public confidence requires transparent processes and consistent adherence to established ethical and legal standards.
Key Market Segments
The Blood and Organ Bank Market is segmented by product, end-user, and region. Each segment addresses different clinical requirements and operational needs within the healthcare system.
By Product
Blood Banking – Non-Umbilical Cord Blood: This segment includes the collection, processing, testing, storage, and distribution of conventional blood and blood components. Red blood cells, platelets, and plasma are important for transfusions, surgical procedures, trauma treatment, and the management of various medical conditions. Demand is influenced by hospital admissions, surgical volumes, emergency care requirements, and the prevalence of blood disorders.
Blood Banking – Umbilical Cord Blood: Umbilical cord blood banking focuses on collecting and preserving blood obtained from the umbilical cord and placenta after childbirth. These samples can contain stem cells used in selected transplantation procedures. The segment includes public and private banking models, with demand shaped by awareness, healthcare access, collection programs, and the clinical use of cord blood-derived cells.
Organ Banking: Organ banking and related procurement and preservation services support transplantation by coordinating donor identification, organ recovery, compatibility assessment, preservation, and transportation. Growth in transplant capabilities and improvements in organ preservation technologies are important factors influencing this segment. Effective coordination remains essential because organ suitability and viability can change with time and handling conditions.
Tissue Banking: Tissue banking involves the collection, processing, preservation, and distribution of human tissues for approved clinical applications. These materials may support orthopedic surgery, reconstructive procedures, wound care, and other treatments. The segment depends on donor availability, tissue processing capabilities, quality assurance, and compliance with applicable regulations.
Bone Marrow Banking: Bone marrow banking and related stem cell donor services support treatments for selected hematological malignancies, blood disorders, and immune system conditions. Donor registries and compatibility testing help identify suitable donors for patients requiring transplantation. Demand is influenced by clinical need, registry participation, access to specialist treatment, and improvements in transplant medicine.
Other Banking: Other banking services include specialized biological material storage and related activities that do not fall within the primary categories. Their contribution varies according to the scope of services offered by providers and the development of new medical applications.
By End-User
Hospitals: Hospitals are major users of blood and organ banking services because they conduct surgeries, emergency treatments, transfusions, and organ transplantation procedures. Their requirements include timely access to compatible blood products, reliable inventory systems, and coordinated communication with collection centers and procurement organizations.
Diagnostic Centers: Diagnostic centers support the market through laboratory testing, blood group identification, infectious disease screening, compatibility assessment, and other diagnostic services. Advances in molecular testing and laboratory automation can improve testing efficiency and support safer clinical decisions.
Blood Banks: Blood banks are central to the collection, testing, processing, storage, and distribution of donated blood and its components. Their operations depend on donor recruitment, efficient inventory management, temperature-controlled storage, quality assurance, and coordination with hospitals and emergency services.
Others: This category includes specialized transplantation organizations, tissue banks, research institutions, cord blood banking providers, and other healthcare facilities involved in the management of biological materials.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/230114/
Regional Market Performance
North America: North America is expected to hold a leading position in the Blood and Organ Bank Market during the forecast period. The region benefits from established healthcare infrastructure, advanced diagnostic capabilities, organized blood collection networks, and developed organ procurement systems. The United States is an important contributor because of its extensive transplant services and demand for transfusion support. Continued investment in laboratory automation, digital inventory management, and organ preservation technologies is expected to support regional growth.
Europe: Europe represents an important market supported by established healthcare systems, blood donation organizations, transplantation programs, and quality standards. Countries such as Germany, the United Kingdom, France, and Italy maintain extensive healthcare infrastructure and specialized clinical services. Cross-border collaboration, donor recruitment, and improvements in tissue and organ preservation remain important areas of development.
Asia Pacific: Asia Pacific is expected to offer growth opportunities as healthcare infrastructure expands and awareness of blood and organ donation increases. China, India, Japan, South Korea, and Australia represent important markets with varying levels of healthcare access, donation infrastructure, and transplantation capacity. Investment in collection facilities, laboratory services, digital registries, and cold-chain infrastructure could help address regional supply gaps.
Middle East and Africa: Market development in the Middle East and Africa is influenced by healthcare investment, public awareness, specialized treatment availability, and the development of national donation programs. Differences in infrastructure and access to trained personnel remain challenges in several markets. Expansion of hospital networks and improved coordination among healthcare organizations may support gradual growth.
South America: South America benefits from expanding healthcare services and established donation and transfusion programs in several countries, particularly Brazil and Argentina. Continued investment in blood collection, testing facilities, donor registration, and transplant services can improve access to essential biological materials.
Major Industry Players
The Blood and Organ Bank Market includes plasma collection companies, blood donation organizations, cord blood banking providers, tissue banking organizations, and transplant support institutions. Competition is shaped by collection capacity, quality assurance, laboratory technology, geographic coverage, operational efficiency, and partnerships with healthcare providers.
Key companies and organizations identified in the market include:
-
BioLife Plasma Services – United States
-
CSL Plasma – United States
-
Octapharma Plasma – United States
-
Sanquin – Netherlands
-
Interstate Blood Bank – United States
-
Be The Match – United States
-
Australian Red Cross Lifeblood – Australia
-
OneBlood – United States
-
Scottish National Blood Transfusion Service – United Kingdom
-
Canadian Blood Services – Canada
-
American Red Cross – United States
-
New England Organ Bank – United States
-
21st Century Medicine – United States
-
New York Blood Center – United States
-
The Living Bank – United States
-
Musculoskeletal Transplant Foundation, Inc. – United States
-
National Organ & Tissue Transplant Organization – Canada
-
China Cord Blood Corporation – China
-
New York Cord Blood Program – United States
-
Cord Blood Registry – United States
Market participants pursue growth through investments in collection and processing facilities, technology upgrades, partnerships, service expansion, and improvements in storage and distribution. Diagnostic companies and medical technology manufacturers also contribute to the ecosystem by supplying blood typing systems, molecular testing platforms, refrigeration equipment, and organ preservation technologies.
The competitive landscape includes organizations with different operating models. Plasma collection companies focus on collecting plasma for further processing, while nonprofit blood services generally support transfusion systems. Organ procurement organizations, tissue banks, and cord blood providers address more specialized clinical requirements. Consequently, competitive positions should be assessed according to each organization's specific services rather than treating all participants as direct competitors across every market segment.
Strategic developments involving compatibility testing, automated preservation, and digital donor management illustrate the importance of innovation in this industry. Partnerships between diagnostic developers and technology providers can help improve testing workflows and transplant planning. However, individual corporate transactions and product launches should be assessed against official company announcements and regulatory disclosures before being treated as completed developments.
Frequently Asked Questions (FAQs)
1. What is the projected size of the Blood and Organ Bank Market by 2034?
The Blood and Organ Bank Market was valued at USD 18.51 billion in 2025 and is projected to reach nearly USD 29.72 billion by 2034, growing at a CAGR of 5.4% during the forecast period from 2026 to 2034.
2. What are the major factors driving the Blood and Organ Bank Market?
The primary growth drivers include rising demand for blood transfusions and organ transplantation, the increasing prevalence of chronic diseases, improvements in medical technology, government-supported donation initiatives, and the adoption of digital inventory and preservation systems.
3. What are the major restraints affecting market growth?
The market faces challenges related to donor shortages, high infrastructure and operating costs, regulatory compliance, logistical complexity, preservation requirements, and ethical or cultural barriers to donation.
4. Which region is expected to lead the Blood and Organ Bank Market?
North America is expected to maintain a leading position, supported by advanced healthcare infrastructure, established blood collection networks, specialized transplant services, and continued investment in diagnostic and preservation technologies.
5. Which product segments are covered in the Blood and Organ Bank Market report?
The report covers blood banking for non-umbilical cord blood, umbilical cord blood banking, organ banking, tissue banking, bone marrow banking, and other banking services.
Conclusion
The Blood and Organ Bank Market is expected to experience steady growth through 2034 as healthcare systems respond to increasing demand for transfusions, organ transplantation, and specialized biological materials. The projected expansion from USD 18.51 billion in 2025 to USD 29.72 billion by 2034 reflects the continuing importance of reliable collection, testing, preservation, and distribution infrastructure.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
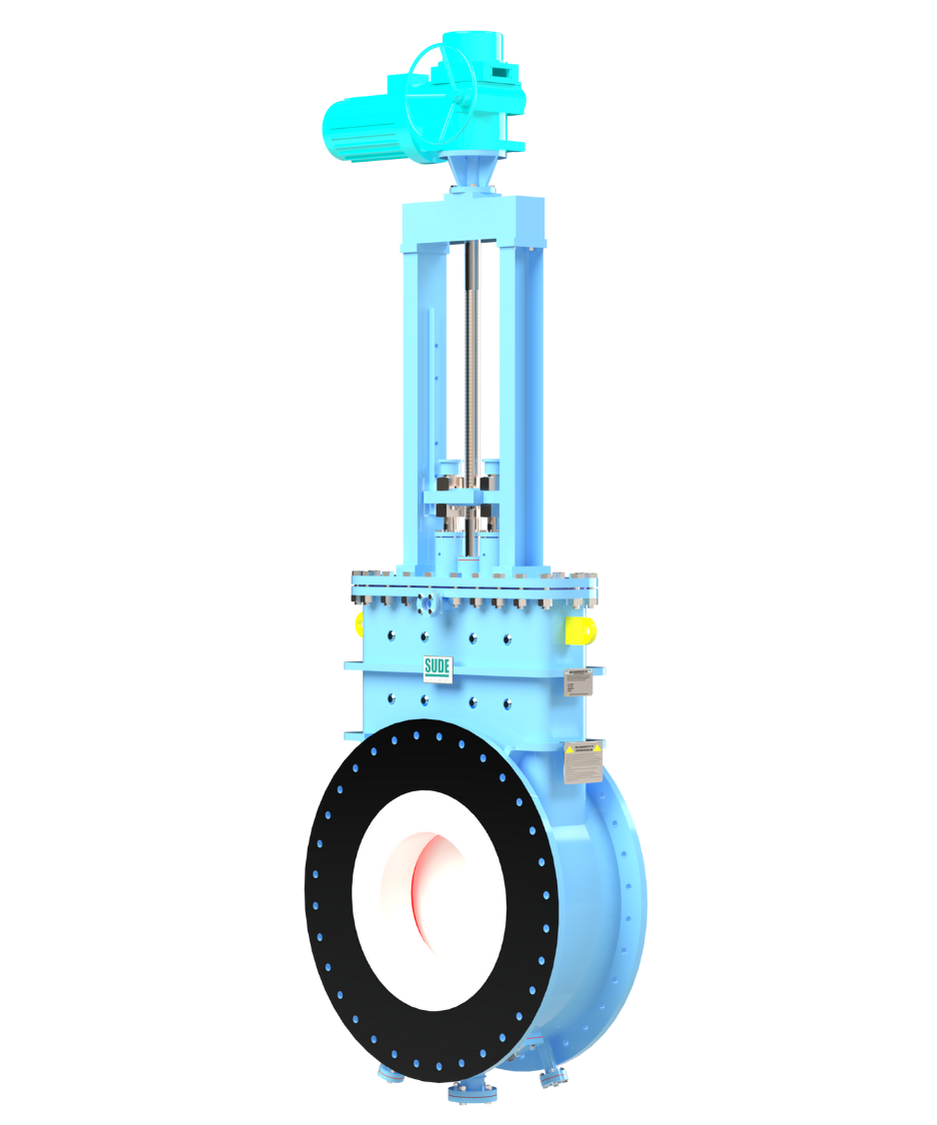
In large industrial facilities, airflow is rarely something that can be left to chance. From controlling gases in process lines to managing air movement through high-temperature equipment, every adjustment can influence production efficiency, energy consumption, and equipment life. A well-designed damper provides the control needed to keep these systems operating consistently, especially when processes involve dust, heat, pressure, or corrosive gases.
This is where modern Butterfly Damper Manufacturer solutions become valuable. Industrial facilities require equipment that can regulate airflow accurately while handling demanding operating environments. Alongside reliable Flow Control Solutions, properly engineered Industrial Butterfly Dampers can support smoother processes, safer operation, and better system performance.
Understanding Butterfly Dampers in Industrial Systems
A butterfly damper uses a rotating disc or blade positioned inside a duct or pipeline. By rotating around its central axis, the blade changes the available passage for air or gas. This simple operating principle makes the damper suitable for applications where flow isolation, adjustment, or regulation is required.
A professional Butterfly Damper Manufacturer considers several factors before designing a suitable product. These can include operating temperature, pressure, media characteristics, duct dimensions, installation orientation, and actuator requirements. The objective is not simply to manufacture a damper but to develop equipment that fits the actual process conditions.
Butterfly dampers can be manually operated or integrated with pneumatic, electric, or other actuation systems. Automated configurations allow operators to adjust airflow remotely and coordinate damper movement with other process equipment.
Why Flow Control Matters in Industrial Operations
Industrial processes often depend on carefully managed airflow. Excessive flow can waste energy, disturb combustion conditions, or affect downstream equipment. Insufficient flow can create pressure problems, reduce process efficiency, and interfere with production requirements.
Modern Flow Control Solutions are therefore designed around the complete operating system rather than a single component. A damper may work together with fans, blowers, filters, ducts, furnaces, boilers, conveyors, and automation systems.
An appropriately selected damper can help operators:
- Regulate airflow according to changing process requirements.
- Isolate sections of a system during inspection or maintenance.
- Improve operational stability through controlled movement.
- Reduce unnecessary pressure losses and energy consumption.
The correct combination of damper construction, sealing arrangement, actuator selection, and control strategy can make a noticeable difference to overall plant performance.
Applications of Industrial Butterfly Dampers
Different industries use dampers according to their individual process requirements. Cement plants, power plants, steel facilities, chemical units, mineral processing plants, and other manufacturing environments may require airflow equipment capable of operating under challenging conditions.
Industrial Butterfly Dampers are particularly useful in ducting and gas-handling systems where space, operating speed, and controllability are important considerations. Their compact design can make them suitable for installations where larger damper arrangements may not be practical.
In high-temperature applications, material selection becomes especially important. Components must be capable of maintaining mechanical integrity under elevated temperatures. In dusty environments, the sealing and blade arrangement must also be selected according to the nature of the conveyed material.
Selecting the Right Butterfly Damper
Choosing a damper should begin with understanding the actual operating environment. A product that performs well in one application may not be suitable for another if the temperature, pressure, media, or cycling frequency differs significantly.
An experienced Butterfly Damper Manufacturer can evaluate these requirements and recommend an appropriate construction. Important considerations may include the required damper size, body material, blade design, shaft arrangement, sealing method, and actuator type.
For automated applications, actuator selection is equally important. Electric actuators can provide controlled positioning and integration with plant automation systems, while pneumatic actuators may be preferred where rapid operation and existing compressed-air infrastructure are available.
Engineering Better Flow Control Solutions
Effective Flow Control Solutions should balance performance, reliability, maintenance requirements, and operating cost. Simply installing a damper does not guarantee efficient flow management. The complete system needs to be evaluated.
For example, an incorrectly sized damper may create unnecessary pressure loss or fail to provide the required control range. Poor sealing can allow unwanted leakage, while unsuitable materials can shorten service life in aggressive environments.
Engineering should therefore consider both normal and exceptional operating conditions. Start-up, shutdown, emergency isolation, cleaning cycles, temperature variations, and maintenance requirements can all influence damper design.
Important Selection Factors
|
Factor |
Why It Matters |
|
Temperature |
Determines suitable construction and materials |
|
Pressure |
Helps establish mechanical requirements |
|
Media |
Influences blade, body, and sealing selection |
|
Size |
Ensures correct installation and flow capacity |
|
Actuation |
Determines manual or automated operation |
|
Sealing |
Helps minimize unwanted leakage |
|
Operating Cycle |
Supports appropriate actuator and component selection |
Benefits of Industrial Butterfly Dampers
One reason Industrial Butterfly Dampers are widely considered for industrial ducting applications is their relatively straightforward construction. A rotating blade provides an efficient method of opening, closing, or regulating a passage without requiring a complicated internal mechanism.
Another benefit is their compatibility with automation. When connected to suitable actuators and control systems, dampers can respond to process signals and help maintain desired operating conditions.
Maintenance is also an important consideration. Access to the shaft, actuator, bearings, seals, and other components should be considered during installation planning. A design that allows practical inspection and servicing can contribute to improved long-term reliability.
Customization for Different Industries
Industrial environments rarely have identical requirements. A cement facility may deal with abrasive dust and high-temperature gases, while a power plant may need precise control of combustion or flue-gas movement. A chemical process can introduce corrosive media that requires specialized material selection.
For this reason, a capable Butterfly Damper Manufacturer should be able to consider application-specific requirements rather than offering only standard configurations. Dimensions, materials, seals, blade construction, actuator arrangements, and connection details may all be customized according to project needs.
Customized Flow Control Solutions can also help integrate damper equipment with existing plant systems. This is particularly valuable for modernization projects where new equipment needs to work alongside older machinery and control infrastructure.
Improving Plant Efficiency Through Better Control
Energy efficiency is becoming an increasingly important consideration for industrial operators. Fans, blowers, furnaces, compressors, and other equipment can consume substantial amounts of energy when operating continuously.
Accurate airflow regulation can help reduce unnecessary system resistance and support more stable process conditions. Industrial Butterfly Dampers can contribute to this objective when correctly sized, positioned, and integrated into the overall system.
However, efficiency should never be considered separately from reliability. A damper must continue performing under actual plant conditions. Selecting the right materials, sealing arrangement, actuator, and maintenance strategy is therefore essential for achieving dependable performance over time.
Conclusion
Reliable airflow management has a direct connection with industrial productivity, equipment protection, and process stability. The right damper can provide controlled movement of air and gases while supporting isolation, automation, and maintenance requirements.
Working with an experienced Butterfly Damper Manufacturer can help industries identify a design suited to their operating conditions. At the same time, well-planned Flow Control Solutions can connect damper technology with the wider requirements of an industrial process.
As industries continue to improve automation and energy performance, Industrial Butterfly Dampers remain a practical option for many demanding air and gas-handling applications. With appropriate engineering, material selection, actuation, and maintenance planning, these systems can deliver dependable flow management across a wide range of industrial environments.
Market Overview
The global Turmeric Gummies Market was valued at USD 82.14 million in 2025 and is projected to reach nearly USD 332.32 million by 2034, expanding at a compound annual growth rate (CAGR) of 16.8% during the forecast period from 2026 to 2034. The market is gaining momentum as consumers increasingly embrace natural wellness products, plant-based supplements, and convenient alternatives to traditional dietary supplement formats.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/213468/
Turmeric gummies are chewable dietary supplements formulated with turmeric extract or curcumin, the principal bioactive compound associated with turmeric. These products are designed to provide a convenient way for consumers to incorporate turmeric into their daily wellness routines without relying on conventional capsules, tablets, or powders. Available in multiple flavours, formulations, and dietary variants, turmeric gummies appeal to consumers seeking accessible and enjoyable supplementation options.
Growing awareness of preventive healthcare, increasing interest in botanical ingredients, and rising demand for functional dietary supplements are supporting market expansion. Consumers are paying greater attention to ingredient transparency, nutritional composition, and product convenience when selecting wellness products. This shift is encouraging manufacturers to develop turmeric gummies with improved formulations, plant-based ingredients, reduced sugar content, and specialized nutritional profiles.
The market also benefits from the increasing availability of dietary supplements through online retail platforms, pharmacies, health stores, and supermarkets. E-commerce channels enable consumers to compare ingredients, product formats, and prices while providing manufacturers with opportunities to reach broader audiences.
However, the industry faces challenges related to curcumin bioavailability, ingredient consistency, manufacturing standards, and consumer expectations concerning product effectiveness. Companies must balance product innovation with quality assurance, regulatory compliance, and transparent communication about potential health benefits.
Market Drivers and Trends
Rising Demand for Natural and Holistic Wellness Solutions
The growing preference for natural wellness products is a major driver of the Turmeric Gummies Market. Consumers are increasingly incorporating dietary supplements into their daily routines as part of broader efforts to maintain general health and well-being. Botanical ingredients such as turmeric have attracted attention because of their traditional use and the scientific interest surrounding curcumin's antioxidant and anti-inflammatory properties.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/213468/
Turmeric gummies combine this ingredient appeal with a convenient delivery format. Their chewable nature, appealing flavours, and portability make them attractive to consumers who dislike swallowing tablets or capsules. This convenience is particularly relevant for individuals seeking simple supplementation routines.
The increasing availability of wellness products through digital platforms and specialty retailers is also improving product accessibility. As consumer awareness of botanical supplements grows, manufacturers have opportunities to expand their product portfolios and target a wider range of wellness-oriented consumers.
Nevertheless, manufacturers must communicate benefits responsibly because the evidence supporting specific health outcomes varies by formulation, dosage, and individual circumstances.
Growing Popularity of Personalized Wellness Products
Personalized wellness is becoming an important trend in the Turmeric Gummies Market. Consumers increasingly prefer products aligned with their dietary requirements, ingredient preferences, and individual wellness goals. In response, manufacturers are exploring specialized formulations that combine turmeric with complementary ingredients such as ginger, black pepper extract, vitamins, and other botanical compounds.
Products positioned around general wellness, joint support, or antioxidant supplementation can help brands differentiate themselves in an increasingly competitive market. However, specific health claims must be supported by appropriate scientific evidence and comply with applicable regulations.
Personalization also extends to dietary preferences. Vegan, gluten-free, organic, and sugar-free options provide manufacturers with opportunities to serve consumers who carefully evaluate the ingredients and nutritional characteristics of supplements.
Innovation in Formulation and Product Delivery
Product innovation is another significant market trend. Curcumin has limited water solubility and relatively low bioavailability, creating formulation challenges for supplement manufacturers. Companies are exploring delivery technologies and ingredient combinations designed to improve the absorption and stability of curcumin.
Research into lipid-based formulations, specialized delivery systems, and combinations with ingredients such as piperine may create opportunities for differentiated products. However, the effectiveness of these approaches depends on the formulation, and improved absorption should not automatically be interpreted as proof of superior clinical outcomes.
Manufacturers are also experimenting with natural colours, fruit flavours, pectin-based formulations, and alternative sweeteners. These developments support product differentiation while responding to consumer demand for more appealing and specialized supplements.
Expansion of E-Commerce and Retail Distribution
The growth of online retail is creating additional opportunities for turmeric gummy manufacturers. E-commerce platforms allow brands to reach consumers beyond traditional retail markets and communicate product information through ingredient descriptions, educational content, and customer reviews.
At the same time, pharmacies, supermarkets, health food stores, and specialty supplement retailers remain important distribution channels. A combination of online and offline sales can improve consumer access and support brand visibility.
Primary Market Constraints
Curcumin Bioavailability and Product Effectiveness
One of the principal challenges facing the Turmeric Gummies Market is the limited bioavailability of curcumin. Although curcumin is widely studied for its biological properties, its absorption and metabolism can limit the amount available to the body after consumption.
Manufacturers must consider ingredient concentration, formulation stability, processing conditions, and storage requirements when developing gummy supplements. The gummy production process can also introduce challenges related to heat exposure, moisture, texture, and the stability of active ingredients.
Developing formulations that maintain consistent ingredient levels throughout a product's shelf life requires investment in research, testing, and quality assurance. Companies that cannot demonstrate reliable product quality may find it difficult to establish lasting consumer trust.
Ingredient Sourcing and Quality Control
Turmeric extract quality can vary depending on agricultural conditions, processing methods, supplier practices, and the standardization of curcumin content. Inconsistent raw materials can affect formulation performance and finished-product quality.
Manufacturers must establish dependable supplier relationships and implement appropriate testing procedures to verify ingredient identity, purity, and consistency. Testing for contaminants and monitoring manufacturing conditions are also important components of responsible supplement production.
Organic and sustainably sourced ingredients may create additional procurement challenges, particularly when manufacturers need to maintain consistent supply volumes while controlling production costs.
Regulatory Compliance and Consumer Trust
Dietary supplements are subject to different regulatory frameworks across international markets. Requirements concerning product composition, labelling, ingredient safety, advertising, and health claims can increase the complexity of market expansion.
Companies must ensure that marketing communications do not imply unsupported disease-treatment benefits. Clear ingredient declarations, accurate dosage information, and responsible product positioning are essential to maintaining consumer confidence.
Competition from turmeric capsules, powders, tablets, and other botanical supplements also places pressure on gummy manufacturers to demonstrate the convenience and distinctive value of their products.
Key Market Segments
The Turmeric Gummies Market is segmented by type, specialty, distribution channel, end-user, and region. These categories help explain differences in consumer preferences, product positioning, and purchasing behaviour.
By Type
The market is divided into organic turmeric gummies and conventional turmeric gummies.
The organic turmeric gummies segment dominated the market in 2025 and is expected to maintain its leading position during the forecast period. This performance is supported by growing consumer interest in organic ingredients, ingredient transparency, and products perceived as consistent with natural and environmentally conscious lifestyles.
Organic formulations appeal to consumers who prioritize sourcing practices and seek supplements aligned with their broader purchasing preferences. Manufacturers can strengthen this segment through credible certifications, transparent sourcing information, and consistent product quality.
Conventional turmeric gummies also serve an important market role by providing a wider range of formulations and price points. These products can appeal to consumers prioritizing affordability, availability, and established supplement brands.
By Specialty
The specialty segment includes vegan turmeric gummies, gluten-free turmeric gummies, sugar-free turmeric gummies, and other specialty variants.
Vegan turmeric gummies dominated the market in 2025 and are expected to retain a substantial market position during the forecast period. This segment benefits from increasing interest in plant-based products and alternatives that avoid gelatin and other animal-derived ingredients. Pectin-based formulations offer manufacturers an established option for developing plant-based gummy products.
Gluten-free turmeric gummies appeal to consumers who avoid gluten because of medical requirements or dietary preferences. Sugar-free variants target consumers seeking to reduce added sugar intake, while other specialty products may incorporate organic ingredients, alternative sweeteners, or additional botanical extracts.
The growing diversity of consumer requirements creates opportunities for manufacturers to differentiate their products and expand their customer base.
By Distribution Channel
The distribution channel segment comprises online retail and offline retail.
Online retail provides access to a broad selection of brands and formulations. Digital platforms allow consumers to research products, compare prices, review ingredient lists, and purchase supplements from home. Subscription services and direct-to-consumer models may also support repeat purchasing.
Offline retail includes pharmacies, supermarkets, health food stores, and specialty supplement outlets. These channels provide product visibility and allow consumers to examine packaging and seek assistance from retail staff.
An integrated distribution strategy can help manufacturers improve availability and reach consumers with different shopping preferences.
By End-User
The market is segmented into adults and children.
Adults represent an important target audience because of their interest in preventive wellness, botanical supplements, and convenient daily nutrition products. Manufacturers can address this group through varied formulations, flavour options, and clearly communicated ingredient information.
The children's segment represents a specialized opportunity but requires particular attention to age-appropriate formulations, dosage, ingredient safety, packaging, and applicable regulations. Products intended for children must be developed and marketed with appropriate safeguards rather than simply adapting adult supplements.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/213468/
Regional Performance
North America
North America dominated the Turmeric Gummies Market in 2025, accounting for approximately 42% of the global market, according to the provided market estimates. The region's leadership is supported by consumer awareness of dietary supplements, established wellness retail networks, and the availability of a broad range of functional nutrition products.
The United States represents an important market because of its developed supplement distribution infrastructure and strong presence of established wellness brands. Canada and Mexico also contribute to regional demand through retail expansion and growing interest in nutritional products.
The presence of online marketplaces, specialty retailers, and established supplement manufacturers supports product accessibility. Continued innovation in vegan, organic, and reduced-sugar formulations may further strengthen regional demand.
Europe
Europe represents an important market for turmeric gummies, supported by consumer interest in botanical ingredients, product quality, and specialized dietary supplements. Demand may vary across countries according to purchasing power, retail availability, consumer preferences, and national regulatory requirements.
Germany, the United Kingdom, France, Italy, and Spain provide opportunities for manufacturers seeking to expand their presence. Clear labelling, credible quality standards, and compliance with European food supplement requirements remain important considerations.
Asia Pacific
Asia Pacific offers growth opportunities because of the region's historical familiarity with turmeric, expanding consumer markets, and increasing availability of packaged wellness products. India is particularly relevant because turmeric has an established place in traditional food and wellness practices.
China, Japan, South Korea, Australia, and other regional markets offer additional opportunities as manufacturers explore differentiated formulations and digital distribution strategies. However, consumer familiarity with turmeric as a culinary ingredient does not automatically translate into demand for gummy supplements, making product education and market-specific positioning important.
South America
South America provides opportunities for market development as consumers gain access to a wider range of nutritional supplements. Brazil and Argentina are relevant markets for manufacturers exploring regional distribution partnerships and online sales.
Pricing, product availability, regulatory requirements, and consumer awareness will influence the pace of adoption across the region.
Middle East and Africa
The Middle East and Africa market may benefit from expanding retail access and growing interest in health and wellness products. The Gulf Cooperation Council countries and South Africa are among the markets manufacturers may evaluate for distribution and product expansion.
Success will depend on reliable supply chains, appropriate product positioning, compliance with local regulations, and pricing strategies suited to individual markets.
Major Industry Players
The Turmeric Gummies Market includes established dietary supplement manufacturers, botanical wellness brands, and companies specializing in functional gummy products. Competition is influenced by formulation quality, ingredient sourcing, brand reputation, pricing, distribution reach, and product innovation.
Major companies identified in the market include:
-
Goli Nutrition Inc.
-
Nature's Bounty
-
MaryRuth Organics
-
Garden of Life
-
Vitafusion
-
Zhou Nutrition
-
NatureWise
-
Ancient Nutrition
-
Youtheory
-
Gaia Herbs
-
Nature Made
-
Herbaland Naturals Inc.
-
BeLive
-
Trace Minerals
-
NutraChamps
These companies operate across different areas of dietary supplements, botanical nutrition, vitamins, and functional gummies. Their inclusion in the competitive landscape does not necessarily indicate that every company currently offers a dedicated turmeric gummy product in every market.
Competitive Strategies and Growth Opportunities
Product differentiation remains an important competitive strategy. Companies can strengthen their market position by improving formulation consistency, developing distinctive flavours, and introducing vegan, organic, or reduced-sugar products.
Investment in quality assurance and supplier transparency can also help manufacturers address concerns about ingredient purity and product reliability. Clearly documented sourcing practices and appropriate testing procedures may provide a competitive advantage among consumers who closely examine supplement labels.
Digital marketing and direct-to-consumer distribution offer additional growth opportunities. Educational product content, transparent ingredient information, and accessible customer support can help brands communicate product characteristics without relying on unsupported medical claims.
Partnerships with retailers and distributors may improve market reach, while research into ingredient stability and delivery technologies can support the development of differentiated formulations. Companies that align innovation with consumer expectations and regulatory requirements are better positioned to compete in the expanding botanical supplement category.
Frequently Asked Questions
1. What was the global Turmeric Gummies Market size in 2025?
The global Turmeric Gummies Market was valued at USD 82.14 million in 2025.
2. What is the projected market size by 2034?
The market is projected to reach nearly USD 332.32 million by 2034.
3. What is the expected CAGR of the Turmeric Gummies Market?
The market is expected to grow at a CAGR of 16.8% during the forecast period from 2026 to 2034.
4. Which segment dominated the Turmeric Gummies Market in 2025?
Based on the provided market analysis, organic turmeric gummies dominated the market by type, while vegan turmeric gummies led the specialty segment in 2025.
5. Which region held the largest market share in 2025?
North America dominated the market in 2025, accounting for an estimated 42% of the global market.
Conclusion
The global Turmeric Gummies Market is positioned for substantial expansion, with its value projected to increase from USD 82.14 million in 2025 to nearly USD 332.32 million by 2034. The anticipated CAGR of 16.8% reflects growing interest in convenient botanical supplements, evolving dietary preferences, and continued innovation across the functional wellness industry.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
Tank terminals operate continuously, with tasks overlapping. Stocks change, cargo ownership shifts, and safety obligations remain active every shift. Deliveries and dispatches continue while inspections, equipment repairs, and routine maintenance take place across the facility. Keeping these moving parts aligned takes more than traditional tools alone. A cloud platform can provide a shared operational view. By working from connected information, operations, HSSE, maintenance, and finance teams can build a reliable, consistent record that supports daily execution, informed decisions, and audit preparation.
In such a busy setting, information must be easy to retrieve, available when teams need it. Shared records also reduce the gaps created when each department keeps its own version of events. With a common operational picture, staff can coordinate when plans change or several competing tasks need attention.
A tank farm management system provides a central digital workspace for controlling liquid and gas storage activities. Readings from field instruments, including tank levels, pressure, and temperature, can feed into operational processes. Workflows can guide each stage, from raising a nomination through to preparing the final invoice. A software as a service platform can bring records together, make them available remotely, and support growth from one terminal to several sites, including marine facilities, instead of scattering information across spreadsheets and independent applications.
One advantage is a clearer view of what is happening across the terminal. Continuous inventory tracking shows each tank's condition, while automated notifications highlight readings that may need investigation. Changes in ullage, indications of water, or measurements beyond set limits can be brought to the team's attention without depending only on someone noticing them manually. Earlier warnings provide more opportunity to check the cause, take corrective action, and manage a deviation before it becomes a larger operational concern.
Digital access can improve customer experience. Through online portals, customers can check allocations, stock details, and custody transfer information themselves. They need not rely on repeated phone calls, email chains, or exchanges of manually prepared records. Self service access can speed up approvals and reduce routine follow ups, leaving employees more time for work that requires experience, careful review, or direct coordination.
Protecting product quality requires controls at the points where they matter. Validation steps can confirm that the required handling conditions are met during the relevant stages of work. Density verification, established blending directions, and controlled operating limits help teams maintain consistency while products are stored or moved. Clear, well structured processes can also lower the likelihood of routing mistakes, cross contamination, and other errors that may occur during everyday handling.
Mobile tools bring digital procedures into the field rather than keeping them inside the office. At the terminal, workers can complete inspections, record findings, take photographs, and scan barcodes using mobile devices. They can continue capturing information during a temporary loss of connectivity. Once the connection is restored, the records can sync back to the central system. This creates a traceable history of the task, its timing, and the observations made, helping teams understand what happened and providing evidence for audits.
Safety and compliance are more effective when they are part of normal work, not separate paperwork completed afterward. Digital checklists can guide workers through mandatory steps in the correct order, and automated workflows can assign activities in line with approved procedures. Tools that support overfill prevention, emergency shutdown integration, VOC monitoring, and incident reporting can strengthen control measures and help teams maintain compliance across terminal operations.
Shared information can improve financial management. Dashboards can bring together throughput, asset utilization, and profitability measures so decision makers can see operational performance in context. Connections to ERP platforms and APIs can link financial transactions with the events and records behind them. This supports more dependable billing and reduces the mistakes or waiting time that can occur when staff manually transfer data between disconnected applications.
From receipt to dispatch, digital workflows can structure the movements taking place at a terminal. Incoming cargo delivered by pipeline, vessel, or barge can be checked and scheduled before transfer starts. Outgoing loads for trucks and containers can follow controlled steps. Teams can confirm tank availability, receive data from measurement equipment, and identify personnel through tools such as RFID. Internal product transfers and blending can follow methods that support repeatability and compliance. Pipeline workflows can account for pigging, line fill, and interface losses. Where products are packaged, barcode tracking can help maintain visibility during handling, while heating and additive dosing services can be recorded automatically for accurate billing and charges.
Benefits continue after the improvements in coordination. More dependable reconciliation can sharpen inventory records and help limit losses and operating expenses. Planned and predictive maintenance practices can help teams address equipment needs earlier, reducing exposure to unexpected failures and unplanned outages. Better operational planning may also support more careful energy use and stronger performance across the facility.
Having up to date information at hand can shorten the path from question to decision. Employees can review records, documents, and performance measures without waiting for reports to be assembled manually. Access when needed reduces delays and makes processes that once involved several manual handoffs quicker and more repeatable. An operational view also helps staff understand current conditions when a prompt response is required.
Implementation can be simpler when the platform is configured around reusable templates rather than built from scratch. Industry ready options can speed up deployment while allowing each terminal to tailor workflows and settings to procedures. This approach preserves a consistent foundation without sacrificing flexibility, and it reduces the amount of bespoke development needed when the solution is introduced at another location.
Remote access gives supervisors more freedom to oversee work and act on requests from outside a fixed office workstation. They can review activity, approve tasks, and respond to operational needs while maintaining a wider view of terminal performance. Encryption and secured infrastructure can also help protect confidential business and operational records as information moves across the platform.
Teams benefit from the connected environment. Operations staff get better visibility and smoother coordination. HSSE personnel can strengthen oversight of safety requirements and compliance. Maintenance teams can use detailed asset records and mobile access to organize their work. Finance staff can rely on more consistent operational inputs and progress invoices with fewer delays. Customers benefit from clearer access to storage status, allocations, and custody transfer information.
Choosing a terminal management platform ultimately involves bringing operational information, process workflows, safety measures, and analytics into a unified system. The solution should support how the facility works now while allowing its processes to change as needs develop. With a SaaS model, an organization can begin at one terminal and extend a shared approach across other sites, creating a scalable alternative to legacy tools, isolated records, and disconnected workflows.
Book a demo @ https://toolkitx.com/campaign/tank-management/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Why-manual-excel-sheets-are-silently-draining-your-tank-farm%27s-profitability
Quality control becomes harder when essential tasks and records are spread across inboxes, shared drives, and outdated spreadsheets. Instead of spotting concerns early, teams may respond only after something goes wrong. Reports arrive late, patterns are missed, and decisions stall. This can leave quality teams working with an incomplete picture. When quality data lives in disconnected places, it takes more effort to locate defects, recognize recurring problems, and understand the cost of failures.
ToolKitX Quality Management Software (QMS) connects people, processes, and records in one cloud based workspace. When information and workflows work together, organizations can spot trends sooner, act quickly, and trace repeated issues to their source, including supplier related causes. Its modular design lets teams start with priority processes, strengthen existing practices, and expand functionality in stages without disrupting daily operations or switching between separate tools.
A modern QMS provides a framework for planning, executing, monitoring, reviewing, and improving quality activities. It brings together deviation management, audits, document control, corrective and preventive action (CAPA), and supplier performance reviews throughout the quality lifecycle. ToolKitX offers these capabilities through cloud modules that can be used separately or linked as needs develop. This helps organizations improve quality management while keeping expansion manageable.
The system is built around a shared source of quality data. Keeping records in one place supports consistent reporting across internal teams, customer facing activities, and supplier processes. It also reduces uncertainty about which record is current. Users can capture information on different devices, even offline, so tasks need not stop when a connection is unavailable. Automatic timestamps, version histories, and lifecycle tracking preserve accountability from record creation through closure.
Audit activities can follow repeatable methods using reusable checklists tailored to company procedures or regulatory expectations. A common approach makes assessments more consistent across sites, teams, and work types. Each finding can become an action with an owner, due date, and escalation path. Photos, documents, and other evidence stay linked to the relevant audit item, simplifying review and verification, while helping teams document closure more clearly.
Up to date information helps managers make better informed decisions sooner. Live visibility into compliance, operational results, and document status reduces manual follow up. Configurable dashboards highlight priority concerns, while built in statistical process control (SPC) tools help teams examine patterns as results accumulate. Document controls support use of approved materials through review steps, revision histories, and safeguards against outdated versions. This gives employees a clearer basis for consistent decisions.
CAPA processes guide teams through immediate containment, root cause investigation, corrective action, and effectiveness checks. Supplier quality can be assessed through scorecards combining inspection findings, delivery results, and field outcomes. Suppliers can use the shared platform to provide certificates, respond to corrective requests, and complete agreed tasks. This coordinated approach provides a view of supplier performance and responsibilities.
Built for practical work environments, ToolKitX connects with enterprise platforms such as ERP, MES, and PLM through open APIs. These links reduce repetitive data entry and help keep information consistent across systems. The mobile friendly interface and offline access let field personnel record concerns, collect evidence, scan identifiers, and take photos without continuous connectivity. When service returns, captured information synchronizes automatically.
Bringing quality work into one system helps teams identify risks and performance weaknesses earlier. Reviewing defect patterns, yield figures, and supplier results supports intervention before issues escalate. Automated alerts and reminders keep actions moving, limiting delays and rework. Consistent processes can reduce waste, control warranty risk, and expose overlooked operating costs. Centralized documentation also helps maintain audit readiness.
ToolKitX serves organizations in utilities, construction, telecommunications, manufacturing, offshore operations, and service industries. It digitizes inspections, supports compliance, connects operational information with improvement initiatives, and gives teams a dependable source for quality records.
Its cloud architecture supports controlled access through single sign on (SSO), multi factor authentication (MFA), and role based permissions. Organizations can begin with a focused need, such as defect tracking or audit management, then add capabilities like SPC, supplier quality, or complaint management as priorities change. Since modules share a common database, teams can manage the quality lifecycle through one connected, scalable environment that grows with the organization and supports long term improvement.
Book a free demo @ https://toolkitx.com/campaign/quality-management/
Managing high risk work takes more than filling in paperwork. It requires a safeguard that helps keep people safe before a job begins. A digital Permit to Work (PTW) solution organizes hazardous activities within a defined, controlled process. Instead of depending on scattered emails, paper forms, or separate applications, teams can handle the sequence from raising a permit to securing approval and confirming precautions—in one workspace. Bringing these steps together improves visibility, establishes accountability, and preserves a record of decisions and actions.
At the heart of a digital permit to work system is a planned stop before non routine or dangerous work gets underway. This pause is a protective measure, not needless waiting. It gives everyone involved time to examine the job, consider hazards, and confirm that the required precautions are ready. For tasks such as hot work, confined space entry, electrical isolation, working at height, and excavation, this checkpoint helps prevent essential safeguards from being overlooked. Digital PTW processes reinforce the practice through consistent, repeatable steps. Clear responsibilities lead workers through hazard reviews, isolation needs, required tests, and permission to proceed.
The benefits become apparent at busy sites where several teams, contractors, and overlapping jobs operate simultaneously. Under these conditions, paper based processes can be hard to coordinate, creating uncertainty, missed details, and blind spots. A shared platform brings permits, hazard information, authorizations, and supporting records into one location. It captures each activity as it happens, creating a dependable audit trail. Permit status lets teams follow work, coordinate shift changes, and sustain continuity between crews. Safety personnel can see which jobs remain underway, and managers can access complete records with precise time stamps.
To be useful in operations, a PTW platform needs more than digital forms. Adaptable templates allow each permit category to address its conditions. Hazard checklists, isolation instructions, personal protective equipment (PPE) requirements, and risk assessment guidance can be built directly into the process. Approval routes based on user roles reinforce authorization rules and protect the reliability of permit records. Dashboards bring active permits, progress states, delays, and outstanding actions into a single view. Teams can associate permits with equipment, drawings, photographs, and documents, while version tracking and secure storage help keep information controlled. Integrations with lockout/tagout, inspections, incident reporting, and training can connect permit management with the broader workplace safety program.
The permit lifecycle should move through an orderly sequence, from initial planning to final closeout. First, teams describe the job, assess hazards, select controls, and attach documentation. Risk reviews and mitigation planning can then be completed before the permit reaches the people assigned to approve it. Before work begins, the record should confirm worker competency, toolbox talks, gas test results, and PPE checks. While the job is underway, the permit remains available for updates, changing site conditions, and authorization extensions when needed. Once the task ends, isolations are removed safely, the work area is left in an appropriate condition, records are closed, and lessons learned are captured for future use.
An effective PTW program combines organization wide consistency with room for site specific needs. Central safety teams can establish common requirements, while local locations adjust the controls to reflect their operating realities. Flexible templates, access permissions, and validation checks help maintain agreed safeguards without introducing avoidable administrative work or slowing operations unnecessarily.
When implemented well, digital PTW creates benefits across the business. Operations and maintenance crews can obtain decisions more efficiently and reduce avoidable downtime. Safety specialists gain stronger oversight and can retrieve documentation more easily during audits. Site managers and asset owners can support consistent procedures across different shifts and contractor teams. Contractors and suppliers also receive clearer instructions and a more organized onboarding process, making it easier for everyone to plan and coordinate work together.
Organizations still using paperwork or disconnected applications can move toward digitization in stages rather than changing everything at once. They can begin with commonly issued permits, such as hot work, confined space entry, and electrical isolation, then build from that starting point. Processes for lockout/tagout, inspections, and training can be brought into the same workspace. Mobile access helps field personnel manage permits where the work is taking place, while collected records can reveal repeated hazards and areas that need attention. Step by step, this approach creates a more connected permit process, strengthens coordination, and supports continuous improvement in workplace safety.
Book a free demo @ https://toolkitx.com/campaign/permit-to-work/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Refinery-tank-farms-management:-the-digital-imperative-for-safety-and-profit
https://toolkitx.com/blogsdetails.aspx?title=What-is-a-Confined-Space-Entry-Permit-A-Simple-Guide
As darkness sets in, visibility drops, or high winds make offshore work harder to manage, maritime crews may face conditions in which even a short delay matters. Crew members and supervisors need a clear view, reliable details, and current operational information to respond effectively. ToolKitX is designed for demanding working conditions, helping teams adjust as situations change.
Its cloud first design brings live asset tracking and operational supervision together in a single digital workspace. Rather than checking several disconnected tools to piece together what is happening, users can view vessels, aircraft, and field teams from one interface, supported by contextual alerts. This shared view helps replace guesswork with decisions informed by current data.
A consistent operational picture lets supervisors compare activity, spot emerging hazards, and coordinate responses without waiting for fragmented reports. It keeps personnel aligned when equipment and teams work in different places. This shared understanding matters most when events unfold quickly.
The platform offers an air traffic management style view adapted to maritime operations . It gathers current information from vessels and supporting assets using AIS, ADS B, GPS, and radar. Data appears on nautical charts, with customizable filters helping users focus on relevant movement instead of an overloaded display. Teams can notice restricted areas, intersecting routes, worsening weather, or unexpected activity as it develops. Shore based coordinators and offshore personnel can therefore work from the same operational picture.
As activity progresses, the interface refreshes details such as position, speed, heading, and status. Supervisors can establish geofences around harbours, offshore installations, work sites, exclusion areas, and environmentally sensitive places. When a chosen rule is triggered—for example, a vessel exceeds a speed limit, crosses a boundary, or misses a planned event—the system can send notifications to desktop or mobile devices, email inboxes, or connected systems. Relevant people get the information they need without being overwhelmed by needless warnings. Movement, speed, and geofence records can also be exported for audits, compliance reviews, and insurance documentation.
Live observation can be paired with playback for a more complete review. Users may start with the wider operating picture, select an individual asset for closer inspection, and replay its journey with speed indicators for a period of up to 90 days. This history can help examine incidents, confirm that services were delivered, and assess operational performance.
Geofencing can do more than outline a boundary. With ToolKitX, teams can build layered conditions using location, speed limits, closest point of approach (CPA), and estimated arrival times. Notifications can be routed to the parties responsible for action, including operators, contractors, port authorities, and HSE teams. More targeted rules help reduce alarm fatigue and make each alert easier to interpret and act upon.
Weather is another important factor in deciding how work should proceed. Integrated weather information displays wind speed, temperature, and sea conditions alongside defined advisory, caution, and stop work thresholds. By comparing actual conditions with agreed operating limits, teams can make better informed choices about continuing, modifying, or temporarily suspending an activity.
A built in CPA engine adds a further safety measure, assessing movement patterns continuously to flag potential collision situations. By surfacing possible conflicts before they become immediate dangers, it gives teams more time to make a correction or coordinate action. Related events can be logged for later investigation, training, and ongoing safety improvements.
Beyond asset locations, ToolKitX provides a shared workspace for overseeing vessels, aircraft, and personnel. Teams can track required credentials and skills, including STCW, HUET, and GWO, in a structured way. Automatic reminders support timely renewals, helping ensure workers hold current certifications and are ready when deployment is required.
Field access is integral to the platform. Its iOS and Android apps bring web capabilities to teams away from the office, even where connectivity is unreliable. Offline features retain the latest asset positions, allowing supervisors to review geofences and handle alerts without a dependable connection.
By consolidating tracking functions, organizations can address blind spots in operational oversight. Combining multiple technologies in a shared environment reduces reliance on separate tools and establishes a common reference point for operations. This can mean quicker responses, better awareness of changing conditions, improved safety, and less downtime.
Compliance activities are included in everyday workflows instead of being treated as a separate process. Vessel movements, alerts, and user actions are captured in a secure, tamper resistant audit trail. Support for international maritime standards and reporting helps organizations retain evidence for regulatory obligations and internal reviews.
The platform can accommodate changing operational demands, from a modest fleet to a complex network of assets. Role based access controls limit each user's view to information appropriate to their responsibilities, supporting a simpler experience while preserving oversight.
Security remains central throughout the system. ToolKitX uses ISO aligned frameworks and GDPR level data protection practices to help safeguard operational and personal information. Encryption protects data as it moves between systems and while it is stored, supporting confidentiality without unnecessarily slowing platform performance.
Implementation planning receives the same attention as daily operations. Before launch, organizations can model ports, offshore passages, wind farms, and shipping lanes. Teams can trial geofences, adjust alerts, and verify workflows against realistic scenarios before going live. This preparation supports smoother deployment, dependable performance from day one, and greater consistency.
Book a free demo @ https://toolkitx.com/campaign/gps-tracking/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Chemical-work-permit-%E2%80%93-definition,-requirements-and-best-practices
https://toolkitx.com/blogsdetails.aspx?title=Key-responsibilities-of-an-HSE-officer-in-high-risk-industries:-what-every-safety-leader-must-know
https://toolkitx.com/blogsdetails.aspx?title=HSE-management-system-explained:-elements,-benefits,-examples-and-how-to-implement-it-right
Offshore operations are rarely disrupted by one mistake alone. Problems become harder when several arise at once. Changing weather may redirect a helicopter, a supply vessel may miss its arrival window, or a crew member may be unable to travel because their certification has lapsed. Each situation may be manageable alone, but together they can overwhelm coordination methods not designed for constant change.
A modern logistics planning solution gives teams a shared place to manage these moving parts. Transport requests, asset availability, certification details, and updates from vessels, aircraft, and shore staff can be viewed together rather than scattered across separate channels. This fuller picture helps coordinators respond sooner, limit disruption, support safer transfers, and control costs as offshore work grows more complicated. It can reduce repeated calls and follow ups when teams rely on separate sources for updates during busy operations.
The platform provides a central point for organizing personnel, equipment, and cargo throughout each movement. In marine and offshore settings, it can standardize journey planning, approvals, and manifest preparation while tracking who is onboard and managing load distribution. Regulatory checks can become part of everyday procedures instead of an additional task. Combining vessel positions, flight schedules, and weather updates also helps teams spot risks early and act before small problems escalate.
Spreadsheets become less dependable when plans change at short notice. They can work while schedules remain predictable, but port closures, emergency evacuations, and revised timetables may divide important details among several files and versions. If coordinators edit records simultaneously, confusion can arise over timing, capacity, or resource assignments. A dedicated logistics platform reduces this fragmentation by keeping plans in a shared, continuously refreshed workflow, so everyone can refer to consistent information. This shared view can help prevent conflicting bookings and clarify which resources are committed to each movement.
Combining related functions is another benefit. Movement management can follow an activity from its initial request through completion, creating visibility and a traceable record at every stage. Routing tools help coordinators consider cost, safety, and efficiency together. Automated checks can identify duplicate entries or requests that exceed capacity while there is still time to correct them. That creates a clearer history and gives teams a chance to address errors before they affect execution.
Compliance is easier to maintain when it is continuous rather than left until the final review. A central repository can hold essential information such as vessel documents and crew certification records. Hazardous materials can also be tracked, with notifications issued before important items expire. Organizing these details helps teams meet regulatory requirements without relying on personal reminders or rushed manual checks.
Flexibility matters because organizations manage offshore work differently. Platforms of this kind can be configured for operational needs without extensive development. Approval routes, information fields, and business rules can be adapted to fit company structures, equipment, and contractual arrangements. Rather than rebuilding established processes around rigid software, an organization can shape the system to support how work is already carried out.
Other functions can improve oversight and performance. Dashboards bring key information into one view, making conditions easier to assess. Mobile access helps field personnel complete check ins, verify cargo, and handle documents away from a desk. Weight and balance tools reduce separate calculations, while automatic manifest creation simplifies compliance tasks. Weather updates support preparation, and visual schedules with optimization guidance can limit idle time, reduce fuel consumption, and improve resource use. This is especially helpful during handovers between changing shifts.
A typical workflow starts when someone submits a movement request through a portal or connected system, often using a standard form. It then passes through required approval stages, with notifications confirming authorization. During scheduling, live warnings may identify obstacles such as restricted capacity or unfavorable weather, allowing teams to revise plans before work begins. Once the movement is complete, performance details are captured, metrics are refreshed, and the record is securely retained for reporting and audits.
Compared with spreadsheet based planning, a dedicated logistics platform provides a connected operational view. Live status information, automated compliance checks, integrated safety controls, and a traceable activity history sit within the same process. Instead of piecing together fragmented records or relying on assumptions, teams can review what happened, understand why decisions were made, and confirm whether procedures were followed.
This approach is useful for organizations working in demanding, fast changing environments. Offshore energy companies, wind farm operators, and marine logistics teams coordinate movements by sea and air while dealing with shifting schedules, different transport methods, and variable weather. For these operations, a specialized logistics planning system can improve coordination, support compliance, and strengthen control over efficiency and daily execution.
Book a Free Demo @ https://toolkitx.com/campaign/logistic-planning/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=COSHH-explained:-a-practical-guide-for-oil-and-gas,-construction-and-utilities
https://toolkitx.com/blogsdetails.aspx?title=Common-HSE-Challenges-in-the-Workplace-And-How-Modern-Organizations-Overcome-Them
When operational information is scattered across notebooks, long email chains, personal phones, and messaging apps, teams can struggle to build a clear picture of what is happening. Details sit in separate places, and each person may know only part of the story. This lack of shared visibility slows routine work, makes it harder to verify events, and increases the chance that important information will be missed or misunderstood.
A digital logbook brings these details into a common workspace. ToolKitX Log Books allows teams to record observations, site conditions, changes in operations, and supporting images in chronological order. Control room staff, field employees, and people working on mobile devices can refer to the same record. This shared access helps maintain continuity, even when internet or network access is unreliable.
Today’s digital logbooks are not simply paper forms transferred to a screen. They create a living history of activity that can support decisions as work unfolds. Employees can record events as they happen, attach timestamps, and keep information securely available instead of relying on recollection or informal conversations at the end of a shift. ToolKitX also supports digital sign offs, tags, and structured reviews. This makes documentation part of the working process, rather than a task left for later. Teams can verify entries, retrieve details quickly, and recognize recurring problems, communication gaps, or possible warning signs in one consistent place.
Sites in sectors such as energy, utilities, construction, and offshore operations generate information throughout the day. As the volume grows, finding the right detail can take longer and decisions may be delayed. Small issues can also escalate when nobody spots them in time. ToolKitX is designed to help teams handle growing records without adding unnecessary complexity. Search and filtering functions make relevant entries easier to locate, reducing the need to check every record by hand. Built in analytics can surface unusual patterns, allowing teams to investigate concerns sooner. Notifications alert the appropriate people, and supervisors can track actions as they are reviewed, escalated, resolved, or closed. Each step remains documented, providing a dependable audit trail.
For frontline employees, entering information is intended to be straightforward. Dashboards offer a clear view of activity across shifts, making it easier to notice trends, monitor repeat concerns, and understand conditions at a site. Workers can choose an asset or location, assign a priority, add a typed or voice note, and upload relevant files or photographs. Pre set options limit the amount of typing needed, so recording information can fit into everyday work without becoming a heavy administrative task.
Digital workflows can also make shift handovers more reliable. Instead of depending on hurried discussions or notes spread across different places, teams can present handover information in a consistent format. Outstanding actions, risks, approvals, and unresolved matters remain visible to the people taking over. Both outgoing and incoming employees can confirm the handover digitally, reinforcing clear responsibility. In this way, a change of shift becomes a documented transfer of information and accountability, rather than a conversation that may rely on memory.
Since teams have different responsibilities, ToolKitX allows workflows to be configured to suit them. Maintenance staff, safety professionals, supervisors, and operators can adapt templates, categories, and fields to the way they work while remaining connected through the same system. Environmental details, including weather conditions, can be recorded alongside operational updates. Entries can also be linked with relevant permits, inspections, assets, and work orders, so connected information stays together rather than being divided between several applications.
Replacing paper based records and repeated manual steps can make everyday processes more efficient. It reduces duplicate entry, speeds up documentation, and enables reports to be generated automatically. Access controls based on user roles, multiple layers of protection, and automatic backups help protect records from loss or unauthorized viewing. Connections with other systems can also simplify the movement and sharing of information across the organization.
Over time, the information captured during routine work can offer a broader view of operational performance. Staff can enter records from different devices, even while offline, and the information can synchronize once connectivity is restored. Analytical tools can then assess entries for trends, unusual activity, and areas that need attention. Reports may reveal recurring patterns in delays, performance, or incidents. Rather than responding only after an issue has developed, teams can use these findings to act earlier and support safer, more efficient operations.
Centralized digital logbooks are useful for operations managers, supervisors, control room staff, and field teams who depend on accurate information and coordination. A shared record improves visibility, supports smoother shift changes, and makes documentation more consistent. When an event must be checked, its timestamps, photos, notes, approvals, and follow up actions can be reviewed together. This creates a clearer operational history, helping teams make decisions with more confidence and respond quickly as working conditions change.
Book a free demo @ https://toolkitx.com/campaign/log-books/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=RIDDOR-Reporting:-What-Must-Be-Reported-and-How
https://toolkitx.com/blogsdetails.aspx?title=Oil-and-Gas-Hazard-Identification:-The-10-Most-Overlooked-Risks
https://toolkitx.com/blogsdetails.aspx?title=Daily-Workplace-Safety-Checklist-for-Construction-and-Utilities
Market Overview
The global Single Lead ECG Equipment Market was valued at USD 361.09 million in 2025 and is projected to reach USD 483.63 million by 2034, growing at a compound annual growth rate (CAGR) of 3.3% during the forecast period from 2026 to 2034. Market growth is supported by the increasing prevalence of cardiovascular diseases, rising demand for convenient cardiac monitoring solutions, and the expanding adoption of wearable medical devices and remote patient monitoring technologies.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/86186/
Single lead electrocardiogram (ECG) equipment is designed to record the electrical activity of the heart through a single electrical lead. These devices provide a convenient and non-invasive approach to monitoring heart rhythm and identifying potential abnormalities. Compared with conventional multi-lead ECG systems, single lead devices are generally more portable, easier to operate, and suitable for selected monitoring applications in hospitals, outpatient facilities, and home-care environments.
Cardiovascular diseases remain a significant public health concern worldwide. The growing need for early identification of cardiac rhythm abnormalities has encouraged healthcare providers and patients to explore accessible monitoring technologies. Single lead ECG devices can support the detection and assessment of conditions such as atrial fibrillation and other rhythm disturbances, although additional clinical evaluation may be required to establish a diagnosis.
Technological advancements in wireless connectivity, wearable sensors, mobile applications, and artificial intelligence (AI) are expanding the potential applications of single lead ECG equipment. Handheld ECG monitors, wearable patches, and compatible smartwatch technologies allow users to capture cardiac recordings outside conventional clinical settings. These capabilities support more flexible monitoring and can help healthcare professionals obtain additional information about a patient's heart rhythm.
The increasing emphasis on preventive healthcare, personalized medicine, and telehealth services is also creating opportunities for manufacturers. As healthcare systems seek to improve access to cardiac assessments and manage growing patient populations, portable ECG equipment is becoming an important component of decentralized healthcare delivery.
Market Drivers and Trends
Rising Prevalence of Cardiovascular Diseases
The increasing burden of cardiovascular diseases is a major factor supporting demand for single lead ECG equipment. Conditions such as atrial fibrillation, tachycardia, bradycardia, and other cardiac rhythm abnormalities require timely assessment and, in many cases, ongoing monitoring. Single lead ECG devices offer a convenient way to record heart rhythm during routine activities or when symptoms occur.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/86186/
Atrial fibrillation is particularly relevant because episodes may be intermittent and difficult to capture during a short clinical examination. Portable devices can help patients record ECG readings at different times, providing additional information for healthcare professionals. However, single lead recordings are not a substitute for every diagnostic application, and suspicious findings may require a standard 12-lead ECG or further clinical investigation.
Growing Adoption of Wearable and Remote Monitoring Technologies
Wearable healthcare technologies are transforming the way selected cardiac conditions are monitored. Smartwatches, chest-worn devices, adhesive ECG patches, and handheld monitors are increasingly being developed to support convenient heart rhythm assessment.
These technologies allow patients to record cardiac activity without always visiting a healthcare facility. When integrated with mobile applications and telehealth platforms, ECG data can be shared with healthcare professionals for review. This approach may improve monitoring continuity, particularly for patients who require repeated assessments or live far from specialized cardiac care centers.
The expansion of remote patient monitoring is therefore creating opportunities for manufacturers that can combine portability, reliable signal acquisition, user-friendly interfaces, and secure data transmission.
Integration of Artificial Intelligence in ECG Interpretation
Artificial intelligence is emerging as an important trend in the single lead ECG equipment market. AI-enabled algorithms can analyze ECG waveforms, identify patterns associated with selected rhythm abnormalities, and support the interpretation of recordings. Such technologies may help clinicians review large volumes of cardiac data more efficiently.
AliveCor's Kardia platform is an example of a personal ECG technology incorporating automated interpretation capabilities. In addition, developments in advanced ECG signal processing are supporting research into the identification of cardiac abnormalities that may not be apparent through conventional analysis alone.
AI-assisted ECG interpretation still requires appropriate clinical validation, regulatory compliance, and professional oversight where indicated. Nevertheless, continued development in this field is expected to influence product innovation and the competitive positioning of manufacturers.
Increasing Focus on Preventive and Personalized Healthcare
Growing awareness of heart health is encouraging consumers to adopt digital health technologies for personal monitoring. Patients with known cardiovascular risk factors may benefit from monitoring solutions recommended by their healthcare providers, while older adults and individuals experiencing intermittent symptoms may require accessible options for recording heart rhythm.
Healthcare providers are also emphasizing earlier identification of abnormalities and more personalized patient management. Single lead ECG devices can support these objectives by facilitating convenient recordings and providing supplementary information between clinical visits.
Product Innovation and Strategic Collaborations
Manufacturers are investing in device miniaturization, connectivity, signal quality, software integration, and automated interpretation. Strategic collaborations between medical device companies and ECG software developers can help integrate diagnostic algorithms into portable monitoring platforms.
These partnerships may reduce product development timelines, strengthen remote monitoring capabilities, and expand access to cardiac assessment technologies. Regulatory clearances and market-specific approvals remain essential for the commercial adoption of new medical devices and software features.
Primary Market Constraints
Limitations Compared with Multi-Lead ECG Systems
One of the principal limitations of single lead ECG equipment is its restricted electrical viewpoint. Although these devices can be useful for selected rhythm-monitoring applications, they do not provide the same range of information as a conventional 12-lead ECG.
Certain cardiac abnormalities require additional leads, clinical examination, imaging, or laboratory testing. Consequently, single lead equipment cannot replace comprehensive diagnostic systems in every clinical setting. Healthcare professionals must select monitoring technologies according to the patient's symptoms, medical history, and diagnostic requirements.
Accuracy, Signal Quality, and Interpretation Challenges
ECG recordings can be affected by movement, poor electrode contact, electrical interference, and incorrect device placement. Consumer-operated equipment may also produce recordings that are difficult to interpret, particularly when users do not follow the recommended recording procedure.
False-positive alerts can lead to unnecessary anxiety and additional medical consultations, while false-negative results may create inappropriate reassurance. Manufacturers must therefore continue improving signal quality, algorithm performance, and user guidance.
Data Privacy and Cybersecurity Concerns
Connected ECG devices frequently collect and transmit sensitive health information through mobile applications, cloud services, and remote monitoring platforms. Protecting this data is essential for maintaining patient confidence and complying with applicable privacy and healthcare regulations.
Cybersecurity risks, inconsistent data integration, and concerns about unauthorized access may affect adoption, particularly among healthcare organizations with strict information security requirements. Manufacturers must invest in secure data storage, encrypted transmission, appropriate access controls, and transparent privacy practices.
Reimbursement and Affordability Challenges
Although single lead ECG equipment can be less expensive than some conventional diagnostic systems, affordability remains a concern in price-sensitive markets. Costs associated with subscriptions, software services, replacement electrodes, connectivity, and professional interpretation may also influence long-term adoption.
Reimbursement policies vary across countries and healthcare systems. Limited reimbursement for certain remote monitoring applications may discourage providers from expanding their use, especially when the financial benefits are not clearly established.
Regulatory and Clinical Validation Requirements
Medical devices and ECG interpretation software must meet relevant regulatory and clinical performance requirements. Manufacturers entering new geographic markets may face different approval procedures, documentation requirements, and post-market monitoring obligations.
Demonstrating clinical utility, reliable performance, and appropriate algorithm validation can increase development costs and extend commercialization timelines. These requirements are important for patient safety but may create challenges for smaller companies and new market entrants.
Key Market Segments
The Single Lead ECG Equipment Market is segmented by indication, end user, and region. These categories help explain the different clinical applications and purchasing environments influencing demand.
By Indication
Syncope: The syncope segment represents an important application area because unexplained fainting can be associated with cardiac rhythm disturbances. ECG monitoring may help clinicians investigate suspected arrhythmic causes, particularly when symptoms are intermittent. The selection of a monitoring device depends on the frequency of episodes, clinical risk, and the need for additional diagnostic testing.
A systematic diagnostic approach is important because syncope can also result from non-cardiac causes. Single lead ECG equipment may provide useful supplementary recordings in appropriate cases, but it is not sufficient for every syncope evaluation.
Arrhythmia: The arrhythmia segment includes atrial fibrillation, tachycardia, and bradycardia. Increasing awareness of irregular heart rhythms and the need for repeated monitoring are supporting demand for portable ECG technologies.
Atrial fibrillation is a particularly important application because it may occur intermittently and increase the risk of serious complications, including stroke. Single lead ECG devices can help capture rhythm recordings for professional assessment. AI-assisted interpretation and mobile connectivity are further expanding the potential usefulness of these products.
Other Indications: Other applications include selected cardiac monitoring requirements in outpatient care, home healthcare, and follow-up assessments. The suitability of single lead ECG equipment depends on the clinical purpose and the information required by the treating professional.
By End User
Hospitals and Clinics: Hospitals and clinics represent a major end-user category because they require cardiac monitoring solutions for patient assessment, outpatient consultations, and follow-up care. Single lead ECG equipment can complement conventional diagnostic systems where rapid or repeated rhythm recordings are appropriate.
Home-Care Settings: The home-care segment is supported by increasing interest in remote patient monitoring, aging populations, and digital healthcare services. Portable ECG devices allow patients to record selected cardiac information at home and share it with healthcare professionals when supported by the device and care pathway.
Ambulatory Surgical Centers: Ambulatory surgical centers may use ECG equipment for selected pre-procedure assessments, recovery monitoring, and other appropriate clinical applications. Adoption depends on facility protocols, patient requirements, and the need for additional monitoring capabilities.
By Region
The market covers North America, Europe, Asia Pacific, the Middle East and Africa, and South America. Regional performance depends on healthcare infrastructure, cardiovascular disease awareness, digital health adoption, reimbursement frameworks, and access to medical technologies.
Download Sample Pages of Research Overview: https://www.maximizemarketresearch.com/request-sample/86186/
Regional Performance
North America
North America is expected to remain a significant market for single lead ECG equipment due to its established healthcare infrastructure, growing adoption of connected medical devices, and continued investment in digital health technologies. The presence of medical device developers, software companies, research institutions, and specialized cardiac care providers supports product development and commercialization.
The United States is an important market for portable ECG technology because of the availability of consumer-facing health devices and remote monitoring services. Regulatory clearances and clinical evidence can influence the adoption of new products, while healthcare providers increasingly evaluate connected technologies for selected patient monitoring applications.
Europe
Europe is supported by established healthcare systems, increasing interest in remote care, and the adoption of digital medical technologies. Countries such as Germany, the United Kingdom, France, and Italy provide opportunities for manufacturers targeting hospitals, outpatient facilities, and home-care providers.
Demand is also influenced by aging populations and the need to manage chronic cardiovascular conditions. However, market expansion depends on national reimbursement arrangements, medical device regulations, data protection requirements, and healthcare procurement practices.
Asia Pacific
Asia Pacific is expected to offer growth opportunities as healthcare expenditure increases and access to digital health solutions expands. China, India, Japan, South Korea, and Australia represent important markets with differing levels of healthcare infrastructure, technology adoption, and regulatory development.
The growing patient population, expansion of telemedicine, and increasing availability of smartphones and connected devices can support the adoption of portable ECG equipment. Affordable products and localized distribution strategies may be particularly important in emerging markets, where access to specialist cardiac services can vary considerably.
Middle East and Africa
The Middle East and Africa market is influenced by healthcare infrastructure investment, the development of specialized cardiac services, and increasing awareness of cardiovascular disease management. Gulf Cooperation Council countries offer opportunities through investments in modern healthcare facilities and digital health systems.
Across parts of Africa, portable ECG devices may support selected screening and monitoring activities where conventional diagnostic services are less accessible. However, affordability, distribution networks, trained personnel, and reliable connectivity remain important considerations.
South America
South America is supported by demand for accessible cardiac assessment technologies and gradual expansion of digital healthcare services. Brazil and Argentina are among the markets offering opportunities for portable ECG device suppliers. Market development depends on healthcare funding, access to medical equipment, regulatory requirements, and the availability of trained professionals to interpret recordings and manage follow-up care.
Major Industry Players
The competitive landscape includes medical device manufacturers, digital health companies, and developers of ECG monitoring and interpretation technologies. Companies compete through product innovation, portability, connectivity, clinical performance, distribution partnerships, and integration with remote healthcare platforms.
Major companies identified in the Single Lead ECG Equipment Market include:
-
Dimetek Digital Medical Technologies Ltd.
-
AliveCor, Inc.
-
Tianjin Chase Sun Pharmaceutical Group (Beijing Choice Electronic Tech Co., Ltd.)
-
Perlong Medical Equipment Co., Ltd.
-
Ambisea Technology Corp., Ltd.
-
SUZU.K.EN Co., Ltd.
-
Eurocamina
-
Longfian Scitech Co., Ltd.
-
DailyCare BioMedical, Inc.
-
OMRON Corporation
-
Zenicor Medical Systems
-
Medtronic plc
-
LifeWatch AG
-
OMRON Healthcare
-
Lohman Technologies (Cardiac Advancement)
-
iRhythm Technologies Ltd.
-
Reka Health Pte Ltd.
Product portfolios and competitive positions vary across these companies. Some focus on handheld or wearable ECG monitoring, while others participate in broader cardiac diagnostics, ambulatory monitoring, or connected healthcare solutions. The precise scope of each company's participation in the single lead ECG segment should be assessed against its current product portfolio and regulatory approvals.
Recent Industry Developments
Recent product and partnership activity illustrates the market's focus on portable cardiac assessment, AI-assisted interpretation, and remote monitoring. The following developments are based on the supplied market information and should be checked against official company announcements before publication.
-
24 April 2025 — HeartBeam: Announced a strategic collaboration with AccurKardia to integrate the FDA-cleared AccurECG automated interpretation software into its ambulatory single-lead and 3D ECG devices. The collaboration is intended to strengthen automated ECG interpretation and remote cardiac assessment capabilities.
-
24 July 2025 — AliveCor: Reportedly launched its AI-powered Kardia 12L ECG system in India following CDSCO approval. The development highlights the expansion of portable ECG technologies into additional healthcare markets. The product's precise configuration and regulatory scope should be verified before describing it as a single-lead system.
-
13 November 2025 — Withings: Reportedly secured U.S. FDA clearance for BeamO, a multifunctional health-check device incorporating a medically certified single-lead ECG. The device reflects growing interest in integrating cardiac monitoring with at-home health assessment.
-
11 December 2025 — OMRON Healthcare: Reportedly announced an ECG expansion strategy involving investment in Tricog Health and the acquisition of the Heartnote patch service. These activities indicate continued interest in connected cardiac monitoring and ambulatory ECG services.
Frequently Asked Questions
1. What was the global Single Lead ECG Equipment Market size in 2025?
The global Single Lead ECG Equipment Market was valued at USD 361.09 million in 2025.
2. What is the expected market size by 2034?
The market is projected to reach USD 483.63 million by 2034, according to the supplied market estimates.
3. What is the expected CAGR of the Single Lead ECG Equipment Market?
The market is expected to grow at a CAGR of 3.3% during the forecast period from 2026 to 2034.
4. What are the major factors driving market growth?
Key growth factors include the increasing prevalence of cardiovascular diseases, rising demand for portable ECG monitoring, wearable healthcare adoption, remote patient monitoring, and advances in AI-assisted ECG interpretation.
5. What are the major segments of the Single Lead ECG Equipment Market?
The market is segmented by indication, including syncope, arrhythmia, and other indications, and by end user, including hospitals and clinics, home-care settings, and ambulatory surgical centers.
Conclusion
The Single Lead ECG Equipment Market is expected to experience steady growth through 2034 as healthcare providers and consumers increasingly seek accessible, portable, and connected cardiac monitoring solutions. Rising cardiovascular disease prevalence, greater interest in preventive healthcare, and the development of wearable ECG devices are creating opportunities for medical technology companies.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.